Category: Impact investing

  • What it takes to build dreams

    I keep on bumping into the same parallel conversations around the future of the impact investing sector.

    With those in the trenches, what I hear continuously is that it is a long, hard slog.  That companies take a long time to build, that the costs of getting things right are high, that grants and really forward-looking and patient risk capital is key, and that there’s not a straight path from here to there.

    And yet the reports that keep on coming out and the sectoral conversations continue to cheerlead about all the capital that is coming into the space – prevailing estimates for total potential market size by 2020 are in the $500 billion (Monitor Group) to $1 trillion (JP Morgan) range – and to get there, we’re told, impact investing has to become an “asset class.”  Part of getting from here to there, it’s implied, might mean sweeping under the rug the significant segments of impact investing where the economics don’t seem to fully work and where the financial risks are too big relative to the expected financial returns.

    An investor I recently met at a roundtable on understanding and quantifying impact put it simply to me: “anyone who is looking at less than a ‘market’ rate of return is mispricing risk.”

    (Whereas I think the big problem in the world is that we’re mispricing returns by equating returns with what we can see in a discounted cash flow analysis, thereby demoting “impact” to a fuzzy, non-quantifiable something for which it’s not worth taking actual, real risk.)

    Without getting dragged into what is clearly a definitional conversation – namely, until we agree on what we mean by “impact” we can never have a serious conversation about the economics of “impact investing” – I have an observation that keeps on nagging at me: increasingly across sectors I meet more and more people who acknowledge that most of the most important (dare I say the most “impactful”?) work they do has crummy economics.  Getting these projects/endeavors/businesses to happen requires the dogged determination to get many different stripes and flavors of capital to come together, lots of irregular stakeholders to develop a shared vision of the future, and, usually, a healthy dose of subsidy or public funding because there’s a clear public good being created when you succeed.

    And yet in the impact investing sector we often hear that if investors aren’t fully financially compensated for the risks they take, capital will never flow in any serious way.

    If that’s right, how do we explain away the fact that we have managed to create trillions of dollars’ worth of parks or mixed-use developments or hospitals or museums or great schools, most of which don’t make full economic sense but all of which are integral to a vital, vibrant society?  The truth is that markets don’t fully work all the time, and yet huge amounts of capital are regularly mobilized to create things that are worth creating.

    What I’m struggling to do is to better explain, by looking outside our sector, my feeling that the conversation we’re having in the impact investing sector is far too narrow and binary.  When I identify the underpinnings of what makes vibrant, successful societies – you know, all those things that disappeared for a little while when Hurricane Sandy hit – and if I think about all of the incredible pure market plays that have been built on top of the existing infrastructure that was provided by the public sector….well it becomes clear that the “markets” / “not markets” conversation we’re having is far too simple.

    And yet I don’t know specifically which data to look for to help tell this story.   I need more examples across sectors and history, more evidence that helps explain clearly and succinctly what I know to be true: that solving big, intractable problems for disadvantaged communities by and large doesn’t pay (nor should it pay) handsome financial rewards.  And the fact that it doesn’t isn’t some sort of failure of a prevailing orthodoxy, it is in fact a vindication of a rich history of bringing public, private and third sector players together – to bring the best of what each has to offer, including skills and preferences and the right kind of capital – to solve big problems.

    I’ll be talking about some of these questions next month at the Global Philanthropy Forum, and I’d love your great ideas on how to prepare for this talk.

    So, help, please! What are the best examples out there from other sectors (housing, roads, infrastructure, parks, museums, schools, biotechnology, the Internet, telecommunications…) that will bust open this “market return” mindset that is hobbling our thinking about how to create real and lasting change through impact investing?

  • Two sigmoid curves

    At this year’s opening keynote at the SOCAP conference, Katherine Fulton, President of the Monitor Institute, discussed the evolution of the impact investing sector since her last SOCAP keynote in 2007.  If five years ago the sector was all promise and possibility, now Katherine worries that we may be on the verge of a significant downturn.

    Katherine reminded the audience that in 2007, the year the term “impact investing” was coined, one of the main questions we were asking ourselves as impact investors was how we would balance financial returns and social impact.  In Monitor’s analysis, while there was the possibility of high financial returns and high social impact in some areas, by and large impact investing funds would have to decide whether they aimed primarily for social impact with a minimum financial hurdle or primarily for financial return with a minimum social impact hurdle.

    Instead what happened over the last five years was that we mostly opted out of the heavy conceptual and analytical lifting to figure out how best to balance financial and social returns.  Instead, we spent five years pounding the table saying “WE ARE A SECTOR!! NOTICE US!!” and in order to get noticed we told ourselves and the world a story about high financial returns and few tradeoffs.

    Not surprising that we got what we wanted: our sector grew, more funds started flowing in, in 2010 JP Morgan wrote a report claiming that impact investing had $1 trillion in potential, and things kept on accelerating.  In the last few years impact investing has gotten noticed not only by the major development institutions but also the biggest banks in the world and even the world’s billionaires.

    Katherine’s worry, which I share, is that we could be on the verge of a downturn.  Not surprisingly, financial returns are hard to come by, the risks we need to take as investors in this space are high, and lofty expectations are crashing against the realities of what it really takes to build businesses in some of the toughest places on earth serving customers who earn just a few dollars a day.

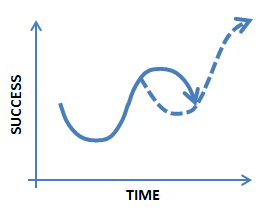
    Borrowing from the work of Charles Handy, Katherine suggested that our sector may be riding a sigmoid curve. (note: here’s a great post that explains sigmoid curves in much more detail)

    We’re on the upswing now, are building momentum and things feel pretty good compared to where we started, but a downturn may be just over the horizon thanks to unrealized expectations – either lower financial returns or, more troubling, social impact not being realized as quickly or easily as the glossy headlines suggested.  Without reinvention our sector runs the risk of not living up to its promise.

    The potential we have as a sector is to jumpstart a second sigmoid curve, building on what we have learned so far.  This begins with the recognition that what we set out to create in the first place was large-scale social transformation using the tools of business (which is NOT the same thing as creating an asset class).


    Drawing this new curve means more, not less, transparency – acknowledging that this is hard and messy work, that we don’t have all the answers, that we are still figuring out how and where financial and social returns are complementary and where there are real tradeoffs.  That’s why the new (dashed) curve slopes downward at first – because the new path is beset with uncertainty and the path we’re on feels safe and familiar.  It’s hard while the music is still playing to ask tough questions, to demand to look at the data early, to ask, when most new funds have been investing for two or three years, why opportunities are hard to come by and ask if investors are willing to take on enough risk to achieve real social impact.

    I agree with Katherine that we have the chance to draw a new curve if we’re willing to look hard at the data.  The Blueprint to Scale report co-authored by Monitor Inclusive Markets and Acumen starts to do this by analyzing what it takes to build large-scale businesses that serve the poor – concluding that most impact investors are unwilling to take early bets on risky new ventures and arguing that we need much more philanthropy if we are going to build out the supply chains and supporting infrastructure these ventures need to succeed.

    What struck me at SOCAP is that our sector is actually willing to have this conversation, but these conversations are nascent.  I’m finding more and more people saying out loud that impact-first funding is incredibly hard to come by, more and more people asking if we need to do much more than tweak around the edges, more and more people saying that if we want radically new solutions then we can’t keep pretending that we are private equity investors with the same old, broken fund structures and the wrong metrics for success.

    The difficult bit is that this conversation is just starting to unfold just at the moment when real money (big banks and pension funds) are knocking on our doors, asking if they can make asset allocations to impact investing at exactly the moment when we’re starting to realize that, by and large, this is not an asset allocation, this is a social change movement.  Or, to put a finer point on things, that there may be sub-sectors where the economics really work and the social impact is significant, but “impact investing” writ large is a very broad space where the risks are high and the timelines are long – and why would we expect otherwise if we’re in this business of helping tackle some of the world’s toughest problems?

    In many ways these potential investors are starting to walk the first sigmoid curve just when we’re trying to draw the second one.  They want to hear about unbridled enthusiasm and no tradeoffs just at the moment when we are collectively realizing that free lunches are hard to come by.  Yes, there may well be some big problems that you can solve while also getting big financial returns, but those aren’t most of the opportunities our sector has found.  If anything we’ve discovered that this is nuanced work, that the companies we are funding are first movers operating in environments where almost no supporting infrastructure exists, and that to get this right we are going to have to roll up our sleeves and get our hands really dirty.  There may be some big financial wins on some distant horizon, but that’s not what we should expect in the next five or ten years.

    And why should it be surprising that solving problems of poverty, of lack of access to energy or water or sanitation, of providing healthcare and safe clean and affordable places to live is never going to be quick or easy or – gasp – particularly lucrative?


  • Dowser 2011 Year in Review interview

    [This interview first appeared on Dowser.org]

    This is the 1st part of our Year in Review Series, in which we reconnect with our group of experts about the trends they forecasted for social entrepreneurship in 2011 and look forward to the year ahead. As the Chief Innovation Officer at Acumen Fund, Sasha Dichter is constantly keeping abreast of significant developments in the social enterprise sector. Acumen Fund, which recently marked its 10th anniversary, has a decade of experience investing in solutions to poverty, and as a result, Dichter has first-hand knowledge of the strength of the investing market. Here he discusses the progress made this year in building a funding pipeline, and what it will take to get more capital flowing to the sector. #

    Dowser: In our interview earlier this year, you said there’s been a gap between the people talking about impact investing  and the amount of investing actually happening.  What is your assessment now?

    Dichter: What’s clear is that more funds are being raised. However, the general theory about what’s going on is that there’s still a lag cycle from talking about it and actually doing it. Anecdotally, we know that more funds have been raised, both in this country and globally, and as expected, people are starting to follow through on this excitement. I would be confident in saying that there have been changes in the investing environment in several countries. There’s a lot of enthusiasm for sure, but it’s still hard to get a benchmark on the volume of investing that’s happening on the ground. #

    In general, would you say that investing in social enterprises has become more commonplace in the past year?
    I think the level of interest is high, but how that’s translating into what people are doing still remains to be seen. The mainstream investors are increasingly aware that the sector exists and are expressing interest and curiosity about it. Ideally what they want is a story that involves little to no tradeoff on the financial returns. The story that people are hoping to be told is that you can invest in this space and do quite well financially, but there is a gap between that hope and the underlying reality of doing this investing. The opportunity and challenge for the sector is to understand and communicate what the real economics of solving social problems are; there is a way to deploy investment funds to solve social problems, but there is no reason to assume that the rewards and risks would be good because these are really tough problems that we’re solving.

    So, how can the sector seize that opportunity?
    I hope we can develop a more nuanced vocabulary around the problems we are trying to fund, for example, communicating to investors what would it really look like to get water to this village in Africa? And, asking them, ‘How would you feel if you could make that happen, and then, What if you got your money back?’ More and more we can tell the story of the success of solving very big problems and sharing the complexities of actually doing this. We are able to say, ‘Here is what we’ve accomplished in the world in terms of changing people’s lives, and by the way, we got you your money back.’ Approaching it from an impact perspective rather than focusing on what types of returns you are getting, will increase action among traditional investors.

    How do you think the funding pipeline for social enterprises has evolved over this year?
    I think the world is still digesting the JP Morgan report [about impact investing as a new asset class], and that has been quite influential for what the sector can look like. At Acumen Fund, we are doing some research with the Montitor Group to try to better understand our portfolio and the different stages of organizational development in funding. The goal is to really understand the types and stages of capital that are needed to create social enterprises, all the way from grant makers, and the public sector players providing smart subsidies, to patient capital and the more mainstream investors. Some of that research has already shown us that there are four stages of funding development for social enterprises. Typically they start with some seed capital and there is a good amount in grant money, and then there is growth capital, and finally the business is at the stage where they can take on a big investment. However, there’s a gap when it comes to Stage 2 and Stage 3 funding for social enterprises.

    One of the questions we need to be asking ourselves is how do we as a sector build a pipeline of Stage 4-ready companies and think about the availability of funding along those stages. There aren’t as many players in the market that have the flexibility and risk appetite to really step in there. When you look at the microfinance sector, $20 billion of philanthropy went into it before it entered the phase where the majority of capital going into the market was investment capital.  So, for social enterprises, where is that philanthropic capital going to come to play? It could be deployed as low return investment capital for example, or there’s a lot of ways to handle it. But what seems to be the case when we talk about the maturity of investment capital out there, that it’s not the stage that investors want to play because it doesn’t align with returns they are looking to get. I think we are still trying to figure out who is going to fill that gap and how.

    Acumen Fund just celebrated its 10-year anniversary, and in our last interview you mentioned this was going to be the year to assess how much impact the organization has had. What have you learned about your progress?
    It’s been a humbling process to reflect on the past 10 years for Acumen Fund. We have $73 million in cumulative investments, and we are seeing capital get returned to us. Ten years ago, this was just an idea to invest in solutions to poverty and now we have this robust sector where we’re talking about the specifics of those investments. We are in a drastically different place in the world now. We still have a long way to go and a lot to do, but we know that patient capital is working and it’s changing people’s lives. The practice of philanthropy looks radically different than it did 10 years ago, not just in the investing sector, but also more widely. The idea that we can use capital in this productive way and we can control it without having it control us to create the outcomes we want is really exciting. The sector offers a certain sense of hope that we can make massive progress in a short time and solve massive problems in very creative ways. It still feels like we are just getting started.

  • FastCompany thinks social impact investing is a crock (with a long aside on cellphones)

    In case you missed it (thanks @beckystraw for sharing it), Anya Kamenetz at FastCompany recently wrote a piece titled “Why Social Investing is a Crock.”

    It’s a pity that in the effort to grab attention, Ms. Kamenetz crossed the line from an attention-grabbing headline to misrepresenting the position of her story’s protagonist, Dean Karlan, author of More than Good Intentions.  Dean’s not saying it’s a crock, he’s saying we haven’t done rigorous analysis yet.  For example, Dean says in his book:

    The social entrepreneurship world is in a weird spot, to be honest with you. It’s a world full of rhetoric about impact investing, yet I have very rarely seen an investor actually take that seriously. When you look at the actual analysis it lacks rigor.

    Let’s be very clear: saying the analysis lacks rigor and saying the sector is “a crock” are wildly different things.  Indeed the analysis mostly does lack the kind of rigor Dean is looking for, specifically because, as Dean rightly points out, “If you want to put a million dollars into a business, are you going to put 33% of that into an impact study?”  The answer is often “no,” except when a funder wants to put up grant money to fund that study (which some are, and more should.)

    More interesting, to me, than laying in to the lame title of this article is to think a bit about randomized control trials (RCTs) – the gold standard in the development space – and their application in the social investment space.  I don’t know the answer here, but I’d like to throw out a question to kick off a conversation:

    What would Dean Karlan say about the “evidence” around the cellphone?

    Meaning, cellphones are an “intervention” (a product, really) that clearly provide benefit to customers.  How much benefit is open to debate, of course, but the question is interesting because the cellphone is the first really new product to achieve mass penetration for low-income consumers (there are now 4.5  billion cellphones globally).

    It feels to me that no one would bother asking in a serious way to do an RCT on cellphones, because it’s no longer anyone’s business to ask that question – because the market has taken over.  The product is appealing enough, consumers have spoken, we can all agree that the ability to communicate via a cellphone creates positive externalities – some economic, some social – and since we’re not using up grant money to pay for it, it stops being the purview of development economists to fret about this.

    I bring up this example because, put in the simplest terms, what social impact investors (at least the ones who really care about social impact) are trying to do is:

    1. Identify products and services that make a material positive impact on the lives of poor people
    2. Create business models that make the cost of providing each incremental product go down to zero…and beyond (meaning, you make a profit).

    Without getting into all of the real complexities of profit maximization versus a “sustainable” rate of return at the firm level; of what to do about all the people who, no matter how cheap the product, won’t be able to pay the full cost; about the role of subsidy; etc; I’d like to posit that there is something fundamentally different about this construct and the construct of analyzing a purely philanthropic intervention.

    No matter what scale a pure philanthropic intervention reaches, the total marginal cost of delivering the nth “thing” (any intervention) is always positive, so you’re in the business of figuring out how the impact relates to that cost and how the impact relates to other similar interventions.  Not so if you find the “next cellphone” – except it’s not a cellphone, it’s safe drinking water or a bio-mass powered light on a mini-grid or a safe and affordable place for a mother to give birth.

    What if we get to the point when it becomes pointless to ask if an intervention “works” because, like the cellphone, it will be ubiquitous, so the question will feel purely [sic] academic?

    What do y’all think?  Am I off my rocker here, or is it possible that creating a scalable businesses that serves the poor is fundamentally different than traditional charity?

  • Is ______ an impact investor?

    On Monday I had the chance to speak at the iiSummit on Impact Investing,  organized by Kellogg and the Chicago Booth School.  It is exciting to see the level of interest in impact investing growing everywhere (beyond the obvious hotbeds of New York, San Francisco, and Washington, DC).  The goal of the conference was to explore how the tools of impact investing could be applied in the Midwest.

    During one of the conference breaks, I had a conversation with a student who wanted my take on whether Bank Rakyat Indonesia, the Indonesian microfinance bank where I worked a decade ago, is an impact investor.

    I was and continue to be stumped by the question, and I think the question sheds light on a worrisome trend in our space.

    Let me explain.

    What the question seemed to be about was whether BRI aims to have social impact, specifically because the interest rates are “high” (~25% p.a.); because it does collateralized lending (as opposed to group lending); and because, it was implied, BRI is highly profit-seeking.

    My take on BRI is a little different: 25% p.a. interest rates are in line with global microfinance interest rates (so I have trouble arguing that they should be lower); limiting itself to collateralized lending does mean that BRI is likely serving the better-off segment of low-income customers, but these customers still clearly have a need for these services;  and, at least when I was there, BRI had a 4:1 ratio of savings to lending – which is only possible because it is a regulated financial institution.   Since I personally think that savings might be more powerful to the poor than lending as a tool to smooth consumption and have capital available for big expenditures (which is really what a lot of microlending is all about), I think this a really big deal.  So, in sum, I’m a fan of BRI from what I saw when I worked there.

    But I digress.

    What the question got me thinking about was that, rather than asking, “Do you think that BRI is having significant, positive social impact?” the question was “Is BRI an impact investor?”

    The implication seemed to be that “impact investing,” as the coolest, hottest trend in our space, is a proxy phrase for doing good work, a notion that was reinforced by the numerous speakers who qualified lots of worthwhile, not-so-new activities (negative screen, public market investing first pioneered by Domini; positive screen, public market investing best represented by Generation Investment Management; CRA lending everywhere; everything that OPIC has done for the last few decades) as “impact investing.”

    Personally, I don’t care what is or is not “impact investing.”  What I care about is whether we are creating positive social change.

    Impact investing, to me, is nothing more and nothing less than the use of investment tools for social ends. Our collective “aha moment” was the realization that investors can strike a deal with sources of capital whereby social impact goals are made explicit.  This allows investors (stewards of others’ capital) to pursue social goals without shirking their fiduciary responsibility to maximize profits.   Volia, we have more tools (not just grants) that we can use to pursue social impact.

    This is simple enough and hard to disagree with.

    But from this perspective, I find myself discouraged by the “finance first” and “impact first” terminology that’s become popular in our space.  It feels trite.  Isn’t the whole point of “impact investing” the “impact” piece?  Without that you have investing – which can create all sorts of impacts (positive and negative; financial and social).  But either you set out to create positive social change or you don’t.  The idea that you’d set out to create only a little positive social change…what exactly does that mean?

    I don’t want to know whether you or I or anyone else is an impact investor. I want to know how much social impact you and I are creating with a dollar (or a euro, or a rupee, or a shilling, or whatever).  Everything else, to me, is just old wine in new bottles.